
An answering service for an insurance company is not handled the moment someone picks up. It is handled when the agent captures the policy number, survives a compliance bar heavier than most categories carry, and has been watched doing both in a live environment before anyone signs off.
One insurer put that last point in plain terms during a demo call, before agreeing to anything. "I'm typically someone who would want to see it like in life scenario right because over time we don't want a situation where we'll be told this can happen then probably when we go live with the solution it's a different ball game."
Everything below traces back to two recorded calls with that insurer, an initial demo and a follow up, scoping an answering service and the quality program that has to sit under it. Nothing here is a guess about what insurance calls need. It is what one insurer said, twice, across two sessions.
The Policy Number Cannot Be Missed
Asked what a call has to capture, the answer arrived fast and specific, not as a general principle. " "
That single line does most of the work of scoping the whole call. A claim status, a coverage detail, a compliance sensitive disclosure, all of it hangs off one verified record. If the policy number is missing or wrong, everything said after it is attached to an account nobody has confirmed.
An answering service that gets the greeting and the tone right but drops the policy number has not had a partial success. It has failed the one check that made the call worth capturing in the first place.
Regulation Runs Heavier Than Usual
The same call named the reason the policy number matters this much. "We operate a very unique as in our industry is very unique and we are very heavy on regulation."
That is not a complaint about paperwork. It is a description of the bar an answering service has to clear before anyone in this sector will trust it with a live call. Most contact centre categories can treat a missed disclosure as a coaching note. An insurer treats it as a compliance event.
Build for that bar from the start. Assume every call may carry a compliance sensitive detail, not just the ones flagged in advance, because that is the standard the insurer scoping this call was already holding its own agents to.
A Grading Sheet Is Not QA
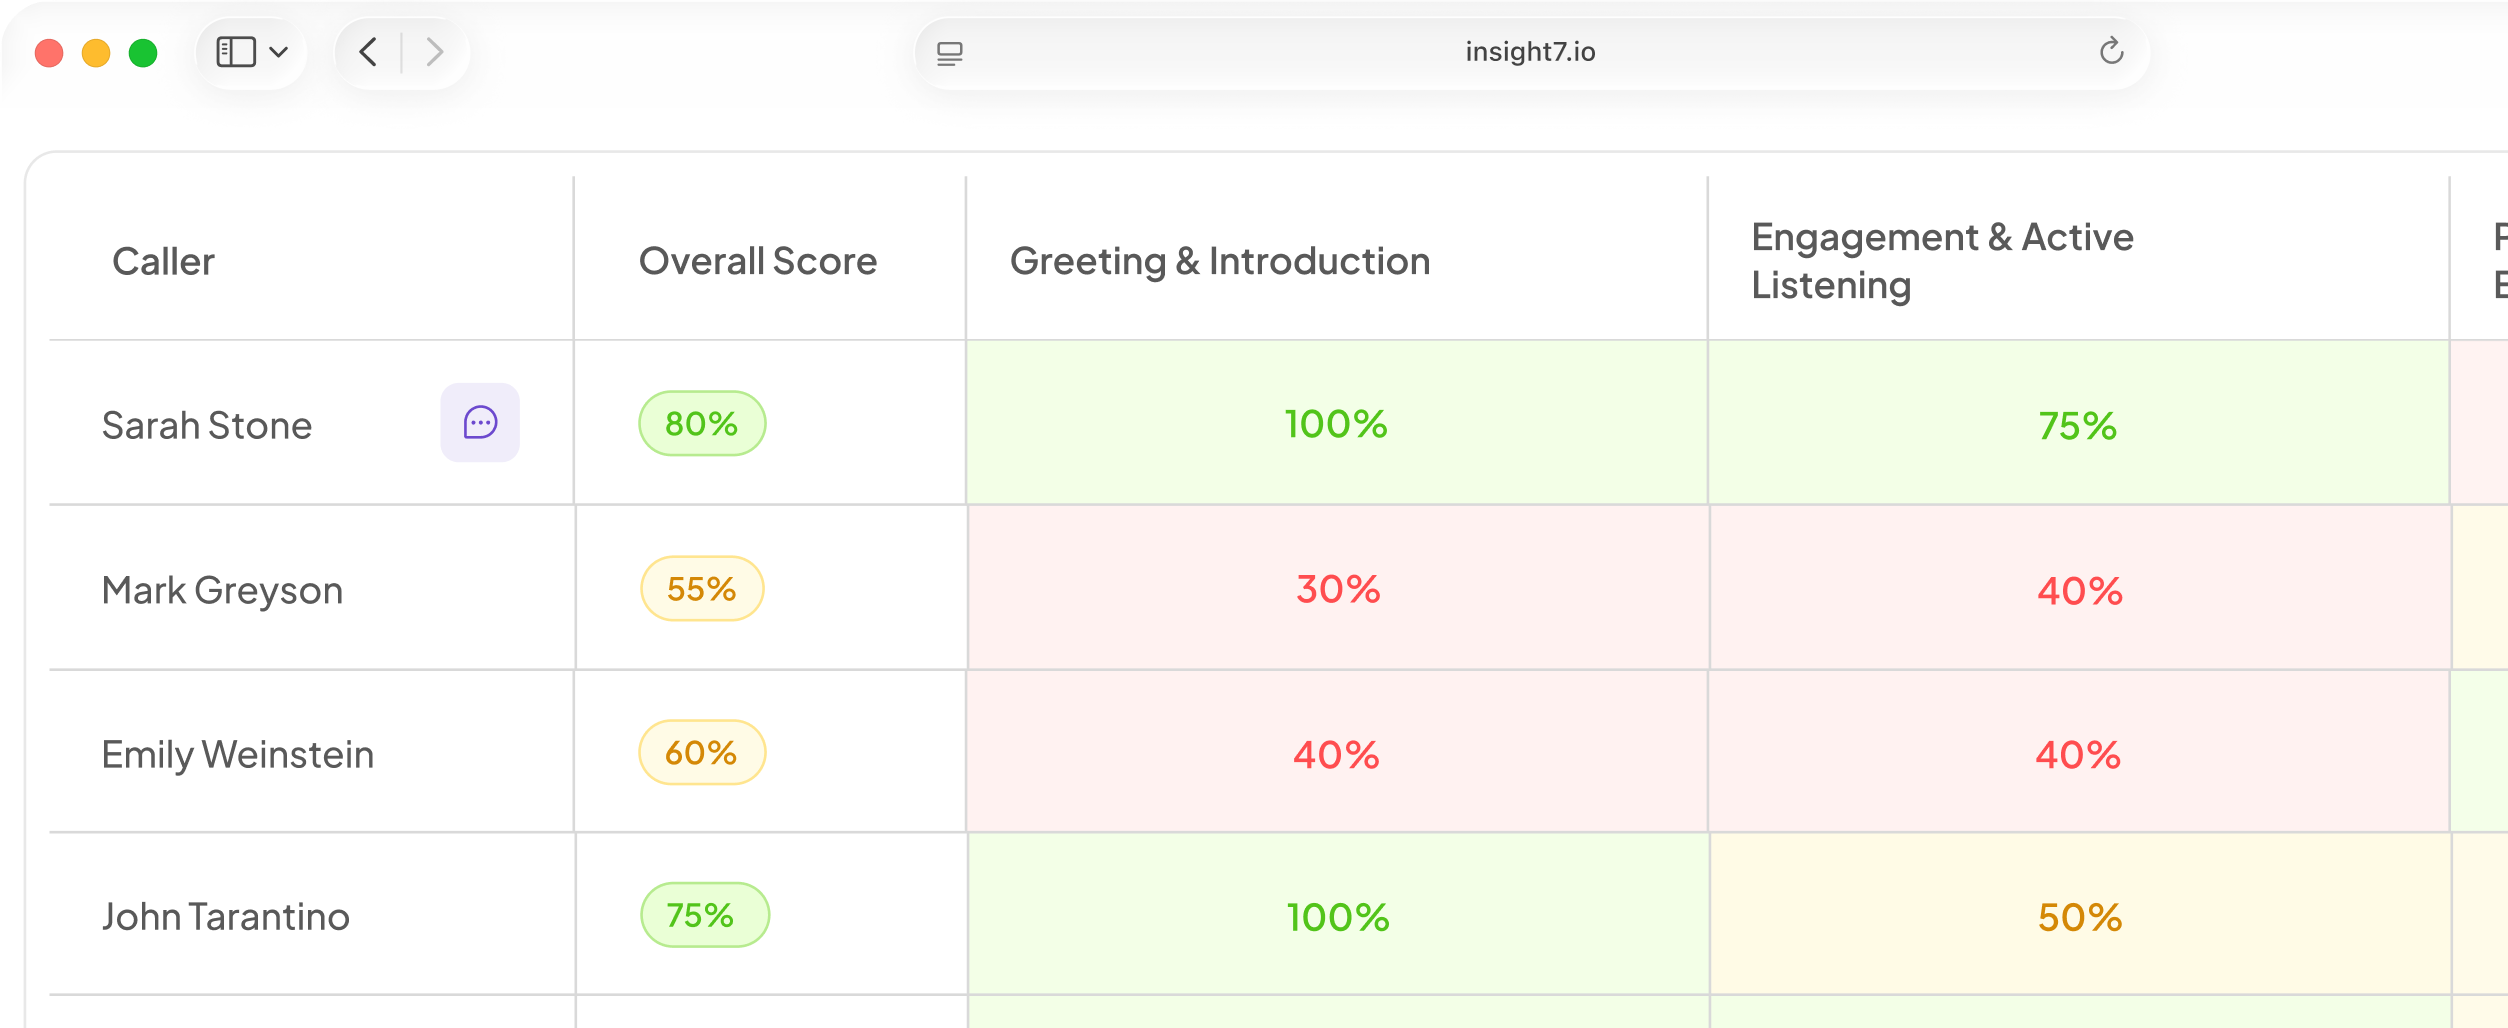
Before this insurer looked at an answering service, its quality process already existed. It runs on manual assessment against a documented SOP, with scores calculated on an Excel grading sheet.
That is a real process and it has been running long enough to have its own documentation. It is also a process that caps how many calls anyone can check, because a human has to listen and score each one by hand.
The gap this leaves is not accuracy. A trained assessor working from a documented SOP can be accurate. The gap is coverage. A grading sheet in Excel scores the calls someone had time to open, not the ones that mattered most.
Live Beats a Demo Recording
The insurer was direct about what would and would not satisfy it before go live. A demo recording was not enough. Seeing the tool behave correctly in a controlled scenario was not enough either.
The requirement was a live environment, run before commitment, where the tool could be tested against real conditions and understood rather than taken on trust. That is a materially higher bar than most vendors are asked to clear, and it is the one this insurer set for itself before anyone else did.
Production Testing Before Any Commitment
The reasoning behind that bar was stated plainly on the same call. The insurer did not want a situation where a capability was described as possible during scoping, only to behave differently once the desk actually went live.
That gap between a scoping conversation and a production call is where most tools quietly fail. A proof of concept run in a sandbox cannot surface it, because a sandbox does not carry the pressure, the accents, the interruptions or the compliance sensitive language a real caller brings.
Ask to run any pilot in a live environment against real call types before you evaluate it, not after. That single condition is what separates a proof of concept from a demo.
Demos Should Sound Like Your Desk
The follow up call raised a related expectation. Each demo should be run in line with the industry being pitched to, so the conversation about call types feels realistic rather than generic.
This matters beyond politeness. A demo built on generic call scripts cannot show you how a tool handles a policy number, a claim reference, or a disclosure specific to your sector. It can only show you that the tool works on calls nobody actually makes.
Before you judge any answering service or QA layer, ask the vendor to run it against your own call types. If they cannot, you are evaluating a different job than the one you are hiring for.
Monthly Testing Already Has a Rhythm
The same follow up call surfaced a second existing process. The team already runs a monthly knowledge management test for its members, and expects any new platform to support that cadence rather than replace it with something unfamiliar.
This is worth naming because it is easy to miss. An insurer scoping a new tool is not starting from zero. It already has a training rhythm, a grading sheet, and a compliance bar it holds itself to. A new platform has to slot into that shape, not ask the team to abandon it.
Ask what QA and testing rhythm already exists on the desk you are scoping for. Whatever you bring in has to sit inside that rhythm, not compete with it.
Recordings Cover Every Session
On the follow up call, one participant asked for recordings of both the earlier session and the current one. In a regulated desk, that request is not a courtesy.
A recording is the artifact a compliance bar depends on. If a decision, a disclosure, or a scoping commitment gets questioned later, the recording is what gets reviewed, not anyone's memory of the conversation. That applies to the calls between you and a vendor as much as it applies to calls with policyholders.
Before you commit to anything, confirm every session, scoping calls included, is recorded and retrievable. An insurer that asked for both of its own sessions was applying its own standard to the vendor relationship, not just to the desk.
What Every Insurance Call Must Capture
Put together, these calls give a short list rather than a long one. Each line below traces to something this insurer named as a requirement, not a general best practice borrowed from another sector.
| What the call must capture | Why it is on the list |
|---|---|
| The customer's policy number | Named directly as the one key parameter agents are monitored against |
| Any compliance sensitive detail, flagged for review | The industry carries a regulation bar heavier than the category assumes |
| A record clean enough to score against an existing SOP | The insurer already grades calls against a documented SOP and expects new tooling to fit that document, not replace it |
| A recording retained for every session, not a sample | Recordings were requested of both scoping sessions, not only the calls being scored |
This list is short on purpose. Adding more lines dilutes the two that matter most, the policy number and the compliance sensitive detail, and those are the two this insurer named without being asked twice.
Handled Means Proven Before Go Live
Given all of this, a handled call is not defined by tone or speed. It is defined by whether the policy number was captured, whether compliance sensitive language was flagged correctly, and whether that behaviour was already proven in a live pilot before the desk went live.
A proof of concept that ran only in a demo environment does not meet that definition, no matter how clean the transcript looks. The insurer said as much directly: what happens in a controlled demonstration and what happens once a solution goes live can be a different ball game.
Any answering service or QA layer scoped for an insurance desk should be judged against that exact sequence. Capture the two required details, prove the behaviour in a live pilot, then go live. Skipping the middle step is the gap this insurer was explicitly protecting against.
Frequently asked questions
Does an answering service for insurance need a different QA form than other industries?
Yes. The regulation bar is heavier, and the parameter list is shorter and more specific. A form built for a general call centre will not check for a policy number or flag compliance sensitive language as a distinct category, and both are non negotiable on an insurance desk.
Should a proof of concept run before or after go live?
Before, and in a live environment rather than a demo one. The insurer scoping this work was explicit that a controlled demonstration proves nothing about how a tool behaves once real calls and real pressure are involved.
What happens to the quality checks that are still done by hand?
Most desks are not starting from nothing. This insurer already runs manual assessment against a documented SOP, scored on an Excel grading sheet, and already runs a monthly knowledge test for its team. Any new tooling needs to sit inside that existing rhythm, not replace it outright.
Who should see the recordings of the scoping calls themselves?
Whoever will later need to defend the decision. One participant in this process asked for recordings of both scoping sessions before deciding anything, which is the same standard a regulated desk applies to the calls it scores.
Scope the list before you buy
If you run an insurance desk, the list above is the one to hand whoever is scoping an answering service or a QA layer for it. Confirm the policy number capture, confirm the compliance sensitive flagging, and confirm the vendor will run a live pilot before go live, not a demo instead of one.
Insight7 can be tested against your own call types before you commit to anything. Book a demo.